A House Appropriations Military Construction bill includes $1.6 billion in funding to continue the VA EHR modernization project.
By Kate Monica
May 13, 2019 – The House Appropriations Military Construction bill for 2020 will allot $1.6 billion to the VA EHR modernization project, up from $1.1 billion in 2019.
VA’s new EHR system will be built on a Cerner platform to enable seamless health data exchange with the Department of Defense (DoD), which uses the Cerner-supported MHS GENESIS system.
“The bill contains $1.6 billion to continue implementation of the VA electronic health record system,” wrote the House Appropriations committee. “This will ensure the implementation of the contract creating an electronic record system for VA that will be interoperable with the system being developed for DOD.”
“These two identical systems will ensure our veterans get proper care, with timely and accurate medical data transferred between the VA, DOD, and the private sector,” the committee continued. “The bill also continues GAO oversight of this program to ensure that the EHR system is implemented in timely manner.”
In addition to enabling interoperability with DoD, VA plans to continually add new capabilities and EHR functionality to the Cerner system to ensure veterans, VA care providers, and community care providers have access to all health IT tools necessary to deliver high-quality care in an ever-evolving digitized healthcare system.
“This bill honors our commitment to the men and women in our armed services, to our veterans, and to the tens of thousands of military families who sacrifice every day for our nation,” said House Appropriations Committee Chairwoman Nita Lowey.
“We are also upholding our promise to America’s veterans by increasing funding for key priorities including healthcare access for women veterans, suicide prevention, benefits, and homeless assistance, so that those who served receive the care and resources they have more than earned,” Lowey continued.
The 2020 appropriations bill will also put $1.5 billion toward military family housing construction and maintenance and $80.4 billion toward VA medical care.
“This bill provides robust funding to support and improve the quality of life for servicemembers and their families, and continues the fight against Russian aggression and emerging threats in the Middle East and North Africa,” said House Appropriations Subcommittee on Military Construction, Veterans Affairs and Related Agencies Chairwoman Debbie Wasserman Schultz.
The bill also highlights the need for increased oversight and accountability over DoD and VA spending.
“Several provisions are included to keep these agencies on track and to address problems that have wasted money and hurt critical services,” wrote the committee.
Improving oversight throughout the VA EHR modernization process is top of mind among several policymakers as the project continues.
In April, Senators John Tester (D-MT) and Marsha Blackburn (R-TN) introduced a bill intended to establish a third-party oversight committee to monitor the EHR modernization project.
The VA Electronic Health Record Advisory Committee Act is designed to help VA maintain transparency and stay on task as it carries out its $16 billion commercial EHR implementation.
“The new electronic health record system is too important to veterans’ health care for the VA to get wrong,” said Tester, ranking member of the Senate Veterans’ Affairs Committee. “Our bill will create another layer of accountability and oversight of the process to make sure the VA roll-out does right by the nine million veterans who will rely on this system.”
The oversight committee would include 11 members who would operate separately from VA and DoD. Committee members would include medical professionals, IT and interoperability specialists, and veterans currently receiving care through VA.
ClimaCell claims its service, which taps into millions of wireless devices, is 60% more accurate than traditional forecasting methods.
by Douglas Heaven
Apr 30
On April 14 more snow fell on Chicago than had been the case in nearly 40 years. Weather services didn’t see the heavy accumulation coming: they forecast one or two inches at worst. But when the late-winter snowstorm hit, it caused widespread disruption, dumping enough snow that airlines had to cancel more than 700 flights across the city’s airports.
One airline did better than most, however. Instead of relying on the usual weather forecasts, it listened to ClimaCell—a Boston-based “weather tech” startup that claims it can predict the weather more accurately than anyone else. According to the company, its correct forecast of the severity of the Chicago snowstorm allowed the airline to better manage its schedules and minimize losses stemming from delays and diversions.
Founded in 2015, ClimaCell has spent the last few years developing the technology and business relationships that allow it to tap into millions of signals from cell phones and other wireless devices around the world. It uses the quality of those signals as a proxy for local weather conditions, such as precipitation and air quality. It also analyzes images from street cameras. It is offering subscribers a weather forecasting service that it touts as 60% more accurate than those of existing providers such as the National Oceanic and Atmospheric Administration (NOAA).
The internet of weather
The approach makes sense, in principle. Other forecasters use proxies, such as radar signals. But by using information from millions of everyday wireless devices, ClimaCell claims it has a far more fine-grained view of most of the globe than other forecasters get from the existing network of weather sensors, which range from ground-based devices to satellites. (ClimaCell taps into those, too.)
The company has now opened a new research center in Boulder, Colorado, where it is developing a new mathematical model that turns cell phone observations into weather data that can be plugged into a simulation. The more accurate your picture of the weather today, the more accurate your forecast for tomorrow.
The model can be tweaked to focus on the region, the type of weather, and the frequency of updates a subscriber wants. That would help renewable-energy companies know how much sunshine is going to hit their solar panels or how much wind will hit their turbines, for example. Better forecasting lets power providers match up supply and demand.
“There’s always a need for better forecasting,” says weather scientist Ken Mylne at the Met Office, the UK’s national weather service. “It’s impossible to do perfect forecasts, but we keep trying to narrow that gap between impossibility and perfection.”
The Met Office is also looking at new ways to measure current weather conditions. The latest version of its simulation, launched in March, uses data from aircraft radar systems, which can provide information about the temperature and humidity of the air that aircraft pass through. “It’s given a significant improvement in forecast quality,” says Mylne.
Yet making use of things like radar and wireless signals is not easy. Mylne says you can’t just put that data straight into the simulation; you have to translate your observation into the most likely weather conditions that fit it. “There is weather information in those signals, but it’s quite deeply buried,” he explains. “Exactly how you use that data is very challenging.”
Mylne thinks that what ClimaCell is doing is a good idea in principle. But he’d like to see many rigorous comparisons with other forecasters in different locations and over several months before he is convinced the technique is as accurate as ClimaCell claims.
Tim Palmer at the University of Oxford in the UK would also like to see more comparisons with other forecasters. “It’s difficult to make a clear judgment on whether they’re doing anything useful or not,” he says. “All weather services are looking for new data, and it’s quite difficult to add value. There’s already an enormous amount of information.”
A spokesperson for NOAA said the organization welcomes new techniques from the private sector but declined to comment on the specifics of ClimaCell’s approach.
In ClimaCell’s favor, Luke Peffers, who heads the startup’s research team in Boulder, has a lot of experience in measuring weather conditions. Before joining the company, he worked for the US government carrying out forensic analyses of the atmosphere to check whether nuclear test bans were being violated. He did that by looking for signs of radiation in the weather.
ClimaCell says it has also performed retrospective simulations for periods of one to 10 years that compare favorably with observations made by others. And it says it tested its model in Israel for a three-month period during heavy floods. “We did a terrific job compared to the Israel Meteorological Service’s rain gauges,” Peffers says.
As well as providing bespoke weather updates to businesses, ClimaCell is interested in collaborating with national forecasters. It is also keen to keep tapping into new sources of data. With more and more devices being connected to the internet, the number of wireless signals is increasing. As the company likes to put it, “Everything is a weather sensor.”
Written by Tajha Chappellet-Lanier
Apr 5, 2019 | FEDSCOOP
While the rollout of 5G wireless capability will be driven by private industry, its emergence has big implications for the Department of Defense, a study by the Defense Innovation Board warns.
The debut of 5G will present many opportunities for the DOD, the DIB says in a new report. It will enable higher capacity for data transfer, increased efficiency, new technologies like hypersonic weapons and more. But it also poses some security risks.
The DIB, an advisory board of tech industry leaders first introduced in 2016, released the unclassified version of this report — co-written by vice president of wireless at Google, Milo Medin, and tech venture capitalist Gilman Louie — Thursday.
The report details the current state of global 5G competition and what the technology will mean for DOD operations. It also includes some recommendations on how the defense agency should proceed. Per its charter, the DIB cannot force DOD to adopt any strategies, but it does make suggestions the agency may choose to follow.
“The shift from 4G to 5G will drastically impact the future of global communication networks and fundamentally change the environment in which DoD operates,” the recent report states. As with past developments, it goes on, there will be a first-mover advantage. And at the moment, China is poised to be that first mover.
“China is on a track to repeat in 5G what happened with the United States in 4G,” the report states.
China’s lead is owing to investment, yes, but the other issue is the lack of spectrum. 5G will require more spectrum availability, and there are two approaches that countries are taking to this. One involves the electromagnetic spectrum below 6 GHz — this is called “sub-6.” The other approach clues in on the part of the spectrum between about 24 and 300 GHz and this is called “mmWave.” China’s efforts are focused on sub-6 while the U.S. is focused on mmWave. Both have benefits and challenges — “the future of 5G may involve some combination of both,” the report states.
However, the report argues, if China moves first with sub-6 and other nations follow that lead, the U.S. might find itself faced with interoperability challenges, not to mention security risks.
“As sub-6 becomes the global standard, it is likely that China, the current leader in that space, will lead the charge,” the report reads. “This would create security risks for DoD operations overseas that rely on networks with Chinese components in the supply chain. Even if the United States were to restrict use of Chinese equipment suppliers domestically, the United States is not a big enough market in wireless to prevent China’s 5G suppliers from continuing to increase market share globally, resulting in significant pressure on a declining set of vendors that would serve the U.S. market.”
The report concludes by suggesting that the DOD “make a plan for sharing sub-6 GHz spectrum,” “prepare to operate in a ‘post-Western’ wireless ecosystem” by adopting a zero-trust network model and advocate for trade policies that serve to secure the supply chain. A fourth recommendation is classified.
The high cost of gene and cell therapies will make it critical for companies to provide higher levels of support for healthcare providers and especially for patients through access, reimbursement, and financing.
The new generation of rapidly emerging gene and cell therapy companies are advancing many promising and potentially curative treatments for major areas of unmet need in healthcare. They are poised to transform the biopharmaceutical industry in the years ahead. A recent report from the Pharmaceutical Research and Manufacturers of America (PhRMA) shows there are nearly 300 novel gene and cell therapies currently in clinical stage development around the world for treatment of a wide range of diseases and conditions, with the majority in oncology.
Some of the most advanced products are being developed by a small number of larger pharmaceutical companies and by innovative small biotechs. In many cases, companies either have, or are building, the range of expertise and resources necessary to advance their products to commercialization. For others, it is essential to consider the full range of options to bring their products to patients and choose the path that will maximize both commercial interests and patient access.
In light of the many risks inherent in “going it alone,” many industry insiders expect to see more M&A deals between small gene and cell therapy companies with late-stage assets and larger entities positioned to handle global commercialization. When assessing their options, there are several factors smaller life sciences companies should consider, including the level of financing required and access to capital to support a commercialization strategy, availability of skilled workers to handle complex manufacturing and distribution processes, the potential need for new levels of innovation and flexibility in pricing models and access strategies, and the need for significant investment in patient and clinician education, monitoring, and support.
Manufacturing and supply chain complexity Among the challenges in development of gene and cell therapies, access to technology is a primary consideration. Alignment with larger companies can provide smaller biotechs access to manufacturing and distribution capabilities that may be out of reach. Conversely, larger companies often seek to acquire innovative development programs to build their pipelines but also expand their R&D capabilities through the acquisition of relevant new platform technologies in the field.
Gene and cell therapy companies are distinct from more traditional drug development programs including small molecules and monoclonal antibodies in that some risks are more significant at later stages of development. In many cases, the final mode of drug delivery for a gene therapy cannot be determined until late in the development program. At the commercial stage, efforts to scale up production to meet demand can also put stress on both manufacturing and distribution protocols.
Efforts to confirm an optimal drug delivery platform and execute production at a large scale require very specialized expertise and advanced manufacturing and supply chain management capabilities that are not readily available to smaller companies. Success will depend on access and optimal use of innovative technologies including advanced cryopreservation tools.
Companies must continually assess their ability to invest in the right technology at the best time – too early and it can squeeze resources needed for other projects, too late and it can affect scale-up when needed. The distribution chain for gene and cell therapies must also reflect the fact that most products have a very short half-life (often days) and require carefully controlled transport conditions.
Sales and marketing Gene and cell therapies will also require new strategies in sales and marketing to support commercialization. While some shifts are beginning to occur, today’s go-to-market models are still mainly relying on an extensive sales force and large marketing and advertising budgets.
But this approach is not suited to gene and cell therapies, especially potentially curative therapies administered in a single dose and targeting very small patient populations in rare diseases. New approaches will require more targeted medical and scientific communications with clinicians but also patients, and other stakeholders, and more precise targeting of patients and healthcare providers.
It will be essential for companies to use predictive analytics to define appropriate patient cohorts and data analyses of diagnoses and procedures to map the patient journey and identify an effective marketing strategy. Companies should be prepared to support sales with a few experts including medical science liaisons rather than a large sales force. These experts will play a vital role in clinician and patient education. In fact, many industry insiders anticipate that a traditional sales force could become obsolete in marketing for gene and cell therapies.
New pricing models Gene and cell therapies are often priced high due to factors including complex production processes, potentially curative efficacy, and the fact that they are designed to treat rare diseases with small patient populations for which there are few, if any, options.
The first approved gene therapy, Glybera, a treatment for patients with the rare lipoprotein lipase deficiency, was priced at $1 million after it was approved. While costs may reflect the benefits that these therapies bring to patients and health systems over time, significant different models may be needed to support payment for the one-time application of a curative therapy. These innovative models include value-based pricing, annuity payments, and expanded risk pools. Many gene and cell therapies also will require payers and clinicians to make decisions related to access and treatment without the levels of long-term efficacy and safety data typically available to support new drugs.
With respect to payment options, value-based agreements require that products meet specific and timed clinical targets to be eligible for reimbursement from payers. This can reduce the risk of coverage for unsuccessful treatments and help address the issue of limited evidence of efficacy and safety at launch. All relevant stakeholders, however, will need to align on what constitutes a successful treatment outcome within a pre-defined time period.
The annuity payment model is another option to pay for the significant long-term benefits of gene and cell therapies. With this approach, payers would agree to coverage based on a series of payments over a set timeline for each patient treated with a curative therapy. This could reduce the near-term budget impact for payers while accounting for longer-term value. As with value-based agreements, annuity payment models would require stakeholders to agree on what constitutes a successful outcome and centralize outcomes data management and reporting, which in itself is a considerable challenge.
Alternatively, to expand risk pools, commercial payers could join with other stakeholders, potentially including government and nonprofits, to help keep premiums and cost sharing at manageable levels. But many payers anticipate that expanded risk-sharing models will face challenges in achieving the necessary levels of broad alignment to be viable.
The high cost of gene and cell therapies will make it critical for companies to provide higher levels of support for healthcare providers and especially for patients through access, reimbursement, and financing. Providing a dedicated access and finance manager who is empowered to support patients will be essential. Some of this type of support is offered today for high priced oncology drugs, and helps patients understand their insurance coverage and additional financial support options, such as foundation support.
Conclusion While the gene and cell therapy sector is trending toward more M&As, many emerging companies might choose to commercialize gene and cell therapies themselves. Success will be based on their ability to refine their go-to-market models, geographic strategies, and maximize efficiency.
Optimal strategies will include acquiring high-value manufacturing processes and technologies at the right time, building a team of specialized experts – which may involve collaboration with and support from key stakeholders – and adopting flexible and innovative pricing models to support treatment. Drug developers will also need to adjust their sales strategies to target a small, specialized audience. While the road to commercialization will include many bumps, efforts to understand and address the unique issues presented by gene and cell therapies can help many companies to find a path forward.
Pascale Diesel is Vice President in CRA’s Life Sciences Practice. Dr. Diesel has 18 years of pharmaceutical and biotech experience in global development, marketing, planning, and business development and more than 10 years of strategic consulting experience focusing on portfolio optimization and valuation. Prior to joining CRA, she was Principal, Strategy and Portfolio Analysis, EMEA at QuintilesIMS (now IQVIA), concentrating on commercial due diligence (sell- and buy-side), sustainable growth and geographic expansion. The views expressed herein are the author’s and not those of Charles River Associates (CRA) or any of the organizations with which the author is affiliated.
The USAF is updating the health IT infrastructure at its military treatment facilities to prepare for MHS GENESIS EHR system implementation because of pilot deployment problems.
April 05, 2019 – The U.S. Air Force (USAF) is updating the health IT infrastructure at its military treatment facilities to prepare for MHS GENESIS EHR system implementation because of problems with a pilot deployment at Fairchild Air Force Base in Washington.
As a result of lessons learned at Fairchild, the Air Force is investing in network upgrades at least six months prior to training and go-live to alleviate technical problems experienced during the pilot MHS GENESIS implementation there, Lt. Gen. Dorothy Hogg, the Air Force surgeon general, told the Senate Appropriations Committee’s defense subcommittee on April 3.
The Fairchild pilot was one of four that the Department of Defense carried out at military facilities in the Pacific Northwest.
Dig Deeper
DoD to Roll Out Next Phase of EHR Modernization This Fall DoD Restructures Management of Medical Treatment Facilities DoD Health Data Exchange Gets Bridge Contract As GAO Hears Appeal
MHS GENESIS implementation “requires broad systems and network improvements, as well as business process changes to achieve standardization and culture change,” Hogg asserted in prepared testimony.
In addition, the Fairchild pilot identified issues with the USAF training program for the new EHR system. “Immature workflows limited training effectiveness for the entire staff, beyond the designated MHS GENESIS ‘super-users’ who were tasked to help other members learn the system. We developed a new training approach in coordination with the Defense Health Agency, informed by the challenges and solutions from Fairchild and the other early sites,” she related.
MHS GENESIS replaces legacy DoD EHR systems, including the Armed Forces Health Longitudinal Technology Application, the Composite Health Care System, and components of the Theater Medical Information Program-Joint.
It will support more than 9.5 million DoD beneficiaries and approximately 205,000 military health system personnel.
All DoD and VA Medical Data Will Stored in Single Database
Stacy Cummings, former program executive officer for the defense healthcare management systems, told the subcommittee that both DoD and the Department of Veterans Affairs (VA) will be using the same Cerner commercial software solution for their EHR systems and will deploy one single instance; all the medical data from the DoD and VA will be stored in a single database.
The MHS GENESIS pilot program, according to Cummings, produced the following improvements: 32 percent increase with the number of patients seen in outpatient care settings; 8.1 percent improvement in turnaround time for chemistry lab tests; 88.5 percent average in discharge medication reconciliation compliance; 84 percent average bar code medication administration compliance; and 63 percent increase in new prescriptions and refills.
Cummings, who is currently the principal deputy assistant secretary of defense for acquisition, said that the MHS GENESIS deployment will occur by region—three in the continental United States and two overseas—in a total of 23 waves. Each wave will include an average of three hospitals and 15 physical locations and will last approximately one year.
This approach allows the DoD to use lessons learned and experience from prior waves to maximize efficiencies in subsequent waves. Full operational capability, including garrison medical and dental facilities, is expected for 2023, she said in her prepared statement.
Cummings related that DoD and VA signed a joint commitment statement in September of last year, pledging to align VA and DoD strategies on deploying an interoperable EHR system. The DoD and VA then evaluated their program elements, including infrastructure, incorporating of clinical and business processes, and other requirements from the functional, technical, and programmatic communities.
To accomplish this integration, the two agencies set up the Federal Electronic Health Record Modernization Program Office, which will provide a “more comprehensive, agile, and coordinated management authority to execute requirements necessary for a single, seamless integrated EHR,” she explained.
The U.S. Coast Guard has joined the EHR implementation as well. The combined DoD-VA-USCG EHR solution will focus on clinical services, interfaces, and a shared infrastructure to enable shared workflows, user roles, order sets, training, and cybersecurity standards, Cummings concluded.
The Obamacare wars have ignored what really drives American anxiety about health care: Medical costs are decimating family budgets and turning the U.S. health system into a runaway $3.7 trillion behemoth.
Poll after poll shows that cost is the number one issue in health care for American voters, but to a large extent, both parties are still mired in partisan battles over other aspects of Obamacare – most notably how to protect people with pre-existing conditions and how to make insurance more affordable, particularly for people who buy coverage on their own.
That leaves American health care consumers with high premiums, big deductibles and skyrocketing out-of-pocket costs for drugs and other services. Neither party has a long-term solution — and the renewed fight over Obamacare that burst out over the past 10 days has made compromise even more elusive.
Democrats want to improve the 2010 health law, with more subsidies that shift costs to the taxpayer. Republicans are creating lower-cost alternatives to Obamacare, which means shifting costs to older and sicker people.
Neither approach gets at the underlying problem — reducing costs for both ordinary people and the health care burden on the overall U.S. economy.
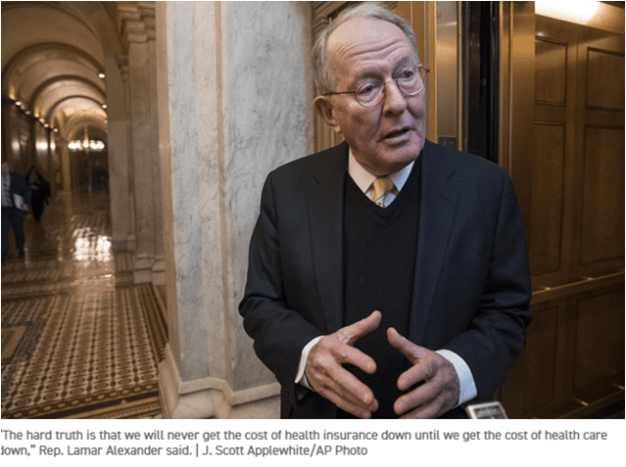
Senate HELP Committee chair Lamar Alexander, the retiring Tennessee Republican with a reputation for deal-making, has reached out to think tanks and health care professionals in an attempt to refocus the debate, saying the interminable fights about the Affordable Care Act have “put the spotlight in the wrong place.”
“The hard truth is that we will never get the cost of health insurance down until we get the cost of health care down,” Alexander wrote, soliciting advice for a comprehensive effort on costs he wants to start by summer.
But given the partisanship around health care — and the fact there have been so many similar outreaches over the years for ideas, white papers and commissions — it’s hard to detect momentum. Truly figuring how to fix anything as vast, complex and politically charged as health care is difficult. Any serious effort will create winners and losers, some of whom are well-protected by powerful K Street lobbies.
And the health care spending conversation itself gets muddled. People’s actual health care bills aren’t always top of mind in Washington.
“Congress is looking at federal budgets. Experts are looking at national health spending and the GDP and value. And the American people look at their own out-of-pocket health care costs and the impact it has on family budgets,” said Drew Altman, the president and CEO of the Kaiser Family Foundation, which extensively tracks public attitudes on health.
But Congress tends to tinker around the edges — and feud over Obamacare.
“We’re doing nothing. Nothing. We’re heading toward the waterfall,” said former CBO director Doug Elmendorf, now the dean of the Harvard Kennedy School, who sees the political warfare over the ACA as a “lost decade,” given the high stakes for the nation’s economic health.
The solutions championed by the experts — a mix of pricing policies, addressing America’s changing demographics, delivering care more efficiently, creating the right incentives for people to use the right care and the smarter use of high-cost new technologies — are different than what the public would prescribe. The most recent POLITICO-Harvard T.H. Chan School of Public Health poll found the public basically wants lower prices, but not a lot of changes to how — or how much — they consume health care, other than spending more on prevention.
Lawmakers are looking at how to start chipping away at high drug prices, or fix “surprise” medical bills that hit insured people who end up with an out-of-network doctor even when they’re at an in-network hospital. Neither effort is insignificant, and both are bipartisan. While those steps would help lower Americans’ medical bills, health economists say they won’t do enough to reverse the overall spending trajectory.
Drug costs and surprise bills, which patients have to pay directly, “have been a way the public glimpses true health care costs,” said Melinda Buntin, chair of the Department of Health Policy at Vanderbilt University School of Medicine. “That information about how high these bills and these charges can be has raised awareness of health care costs — but it has people focused only on that part of the solution.”
And given that President Donald Trump has put Obamacare back in the headlines, the health law will keep sucking up an outsized share of Washington’s oxygen until and quite likely beyond the 2020 elections.
Just in the last week, the Justice Department urged the courts to throw out Obamacare entirely, two courts separately tossed key administration policies on Medicaid and small business health plans, and Trump himself declared he wants the GOP to be the “party of health care.” Facing renewed political pressure over the party’s missing Obamacare replacement plan, Trump last week promised Republicans would devise a grand plan to fix it. He backtracked days later and said it would be part of his second-term agenda.
Democrats say Trump’s ongoing assaults on the ACA makes it harder to address the big picture questions of cost, value and quality. “That’s unfortunately our state of play right now,” said Rep. Raul Ruiz (D-Calif.). “Basic health care needs are being attacked and threatened to be taken away, so we have to defend that.”
The ACA isn’t exactly popular; more than half the country now has a favorable view of it, but it’s still divisive. But for Republicans and Democrats alike, the new POLITICO-Harvard poll found the focus was squarely on health care prices — the cost of drugs, insurance, hospitals and doctors, in that order.
The Republicans’ big ideas have been to encourage less expensive health insurance plans, which are cheaper because they don’t include the comprehensive benefits under Obamacare. That may or may not be a good idea for the young and healthy, but it undoubtedly shifts the costs to the older and sicker. The GOP has also supported spending hundreds of millions less each year on Medicaid, which serves low-income people — but if the federal government pays less, state governments, hospitals and families will pay more.
Last week, courts blocked rules in two states that required many Medicaid enrollees to work in order to keep their health benefits, and also nixed Trump’s expansion of association health plans, which let trade groups and businesses offer coverage that doesn’t include all the benefits required under the ACA.
House Democrats last week introduced a package of bills that would boostsubsidies in the Obamacare markets and extend that financial assistance to more middle-class people. The legislation would also help states stabilize their insurance markets — something that the Trump administration has also helped some states do through programs backstopping health insurers’ large costs.
These ideas may also bring down some people’s out-of-pocket costs, which indirectly lets taxpayers pick up the tab. These steps aren’t meaningless — more people would be covered and stronger Obamacare markets would stabilize premiums — but they aren’t an overall fix.
The progressive wing of the Democratic party backs “Medicare for All,” a brand new health care system that would cover everyone for free,including long-term care for elderly or disabled people. Backers say that the administrative simplicity, fairness, and elimination of the private for-profit insurance industry would pay for much of it.
The idea has moved rapidly from pipe dream to mainstream, but big questions remain even among some sympathetic Democrats about financing and some of the economic assumptions, including about how much of a role private insurance plays in Medicare today, and how much Medicare puts some of its costs onto other payers. Already a political stretch, the idea would face a lot more economic vetting, too.
The experts, as well as a smattering of politicians, define the health cost crisis more broadly: what the country spends. Health care inflation has moderated in recent years; backers of the Affordable Care Act say the law has contributed to that. But health spending is still growing faster than the overall economy. CMS actuaries said this winter that if current trends continue, national health expenditures would approach nearly $6 trillion by 2027 — and health care’s share of GDP would go from 17.9 percent in 2017 to 19.4 percent by 2027. There aren’t a lot of health economists who’d call that sustainable.
And ironically, the big fixes favored by the health policy experts — the ones that Alexander is collecting but most politicians are ignoring — might address many of the problems that keep aggravating U.S. politics. If there were rational prices that reflected the actual value of care provided for specific episodes of illness and treatment, instead of the fragmented system that largely pays for each service provided to patients, then no medical bill would be a surprise, noted Mark McClellan, who was both FDA and CMS chief under the President George W. Bush and now runs the Duke-Margolis Center for Health Policy.
“But taking those steps take time and will be challenging,” McClellan noted. “And they’ll be resisted by a lot of entrenched forces.”
Alice Miranda Ollstein and Adam Cancryn contributed reporting.
How did a private Chinese firm come to dominate the world’s most important emerging technology?
Foreign Policy illustration
A decade ago, in 2009, the Swedish phone giant Teliasonera set out to build one of the world’s first fourth-generation wireless networks in some of Scandinavia’s most important—and technologically savviest—cities. For Oslo, Norway, Teliasonera made an audacious and unexpected choice of who would build it: Huawei, a Chinese company with little presence outside China and some other developing markets.
The same year, Huawei landed an even bigger and more unexpected contract to completely rebuild and replace Norway’s mobile phone network, which had first been built by the global standard-bearers: Ericsson of Sweden and Nokia of Finland. The Chinese upstart eventually completed the world’s most ambitious network swap ahead of schedule and under budget.
To many in the wireless industry, it was a coming-of-age moment for Huawei, and for China. Huawei was no longer just another Chinese catch-up clawing out market share thanks to cut-rate pricing or thriving on stolen intellectual property. Suddenly it had cutting-edge technology of its own and was elbowing aside established European giants like Ericsson and Nokia in their own backyard.
“For the first time, people realized Huawei was not just the cheap option but could compete on quality and price,” said Dexter Thillien, a telecommunications analyst at Fitch Solutions.
Fast-forward to now. In less than a decade, allegedly thanks in part to billions of dollars in support from the Chinese government, the privately held Huawei has become the world’s largest telecom equipment company, last year posting more than $107 billion in revenue from operations in some 170 countries.
More important, Huawei has, by most accounts, taken the lead in the race to develop one of the modern world’s most important technologies: fifth-generation mobile telephony. Unlike its various predecessors, which simply offered consumers the ability to send texts, then to surf the web on their phones, and finally to stream video, 5G promises to revolutionize the entire global economy.
And for perhaps the first time in China’s modern history, Huawei’s growing market share and technological prowess are putting a champion of the Chinese government in a position to dominate a next-generation technology. 5G will offer hugely faster data speeds than today’s mobile technology, which is important for consumers. But 5G will also be the technology that ensures artificial intelligence functions seamlessly, that driverless cars don’t crash, that machines in automated factories can communicate flawlessly in real time around the world, and that nearly every device on earth will be wired together.
5G will be, simply put, the central nervous system of the 21st-century economy.
5G will be, simply put, the central nervous system of the 21st-century economy—and if Huawei continues its rise, then Beijing, not Washington, could be best placed to dominate it.
Huawei’s startling ability to gatecrash what has been until now an exclusive bastion of the developed world has sent shock waves not only through the industry but also through Western capitals. Its success has turned Huawei into a target for the U.S. President Donald Trump’s administration—which is warning that the company’s growing role in global telecommunications networks could enable Beijing to use its control of the world’s digital plumbing to spy on rival nations or steal their commercial secrets.
“5G is turning more into a geopolitical battleground between the United States and China,” said Tim Ruhlig of the Swedish Institute of International Affairs, who researches 5G technologies.
And that raises a key question that remains unanswered: Who is Huawei really working for? While it prides itself on being a private company, Huawei was founded in 1987 by Ren Zhengfei, a veteran of the People’s Liberation Army’s engineering corps, and the Chinese army was an early and crucial customer for the fledgling firm.
Late last month, a critical report by Britain’s 5G watchdog also raised fears that Huawei might prove to be a high-tech Trojan horse. The report concluded that “underlying defects” left the company’s software and cybersecurity systems open to hackers, posing “significant” security issues. Even so, the report mainly blamed sloppy engineering and found no evidence that the vulnerabilities had been introduced at the direction of Chinese authorities; it also stopped short of proposing an outright ban.
Indeed the Trump administration—which has more often than not managed to alienate its longtime allies—is already faltering in its global campaign to isolate Huawei. While a few U.S. allies, such as Australia and Japan, have followed Washington’s lead and already banned Huawei technology, many others are still considering it. The United Kingdom, like Germany, is still weighing the geopolitical implications of purchasing Huawei equipment. Others such as Thailand and South Korea are pressing ahead and letting Huawei launch 5G projects. India, which the United States hopes to use as a counterweight to China, is resisting American calls to exclude Huawei from its networks.
And behind all these fresh worries over Huawei’s seemingly sudden dominance is a simpler question: How did a modest, private Chinese firm that started out three decades ago importing basic telecoms equipment emerge as the arbiter of what is arguably one of the world’s most important technologies?
There’s no single explanation that accounts for Huawei’s success or recent technical prowess. A cost advantage helped, of course. So did state backing, government protection from foreign competitors, and a huge local market, which led to massive and swiftly multiplying revenues. And it could hardly have been mere coincidence that Huawei’s founder, Ren, was a PLA veteran, and Huawei’s first customer proved to be the People’s Liberation Army.
In the end, however, Huawei’s meteoric rise was the result of a broad mix of different policies and decisions—helped along by a few missteps from its Western rivals.
One theme is clear: Throughout its history, Huawei appears to have benefited from state support not available to the company’s Western rivals, though the exact nature of that aid is difficult to quantify, as is the broader relationship of any private Chinese firm to the government.
Because the company is privately held through a complex employee ownership scheme, it doesn’t have the obligation to publish detailed financial reports as publicly listed firms do. But European investigators have found evidence that Huawei may have received a massive $30 billion line of credit from the China Development Bank, among other well-timed financing.
“State-backed finance was crucial in Huawei’s growth.”
“State-backed finance was crucial in Huawei’s growth,” said Matthew Schrader, a China analyst at the Alliance for Securing Democracy at the German Marshall Fund. It helped Huawei sew up the domestic market, which in turn enabled it to expand overseas by offering deep discounts.
Huawei denies receiving direct state aid. Nonetheless, Ren has been upfront about the importance of Chinese industrial policy as key to the company’s growth. Without Beijing’s policy of protecting Chinese companies from aggressive foreign competition at home, “Huawei would no longer exist,” Ren has said.
Huawei’s rise might thus be seen as the latest test in the struggle between two forms of capitalism: open, privatized Western markets versus state-assisted, Chinese-style ones, though this time with an ideological twist, as Huawei is not officially a state company.
Whatever the Chinese government’s role, Huawei was clearly shaped by Ren’s personal vision and ambition. After leaving the army at the age of 39 and working for a state-owned company, Shenzhen Electronics Corp., for four years, Ren secured an $8.5 million loan from a state bank and started Huawei on his own with 14 staffers, the Far Eastern Economic Review reported in a 2000 profile of the company.
He began as an importer of telecommunications switches, a basic networking technology. In 1990, the company started work on its first switch—but rather than partner with a foreign company, which was standard practice in the Chinese telecommunications industry at the time, Ren made massive investments in his company’s research and development wing to build his own products. In the early 1990s, the company is reported to have had 500 research and development staff and 200 working in production—a lopsided ratio—according to an examination of the company’s business history by the analyst Nathaniel Ahrens.
By 1993, the company released the newswitch and picked up the army as a client, providing it with its own telecom network. That contract gave the company an important boost over its rivals, according to the Far Eastern Economic Review. A year later, Ren managed to secure another form of protection from the state. He met with Jiang Zemin, the Communist Party general secretary, and told him that a country without a domestic telecoms switch industry was like a country without a military. “Well said,” Jiang replied, according to Ren’s account of the meeting.
By 1996, under Ren’s prodding, the Chinese government shifted its industrial policy to favor domestic telecommunications companies, keeping foreign competitors out.
In subsequent years, a freed-up Huawei embarked on a ruthless campaign of domestic expansion, signing up local government clients, often in rural areas. The company sold its technology at rock-bottom prices to eliminate its rivals and sometimes even offered its services to government entities for free. By 1998, the company had matched the market share of its principal rival, Shanghai Bell, a foreign joint venture.
Throughout its rise to domestic dominance, Huawei has also thrived in international markets by offering its products at a significant discount compared to its competitors. Access to a huge pool of engineering talent willing to work for lower wages than Huawei’s Western competitors translates into discounts of up to 20 percent for customers. Today, Huawei controls 29 percent of the global telecom equipment market. In the Asia-Pacific region that figure is 43 percent, and in Latin America it’s 34 percent, according to figures provided by the Dell’Oro Group, a market research firm.
And while Huawei’s history has been marred by several cases of technology theft—such as an infamous instance in the early 2000s of stealing Cisco code for router software—experts credit Ren with building Huawei into a research and development powerhouse from the company’s first days.
“A lot of their technical expertise as of late is because they have a lot of smart people,”
“I think “A lot of their technical expertise as of late is because they have a lot of smart people.”said Mike Thelander, an industry analyst and the founder of the Signals Research Group. “You can say a lot of bad things about Huawei, but you don’t throw the baby out with the bathwater.”
Today, Ren says that being a privately held company gives Huawei the freedom to plow more money back into R&D—some $15 billion to $20 billion per year. Some 80,000 people, or nearly half Huawei’s workforce, are dedicated to research and development; tens of thousands alone work at Huawei’s huge corporate campus in Shenzhen.
And in its focus on turning research into marketable products, Huawei compares favorably to Cisco and Google, said Henning Schulzrinne, the former chief technologist at the U.S. Federal Communications Commission. The company’s research organization “is well integrated into the development process,” allowing Huawei to quickly turn research findings into sales, Schulzrinne said.
Huawei is also vertically integrated. Unlike its principal competitors, Sweden’s Ericsson and Finland’s Nokia, Huawei designs nearly every component of 5G technology, including the defining technology of the internet economy: the smartphone. The company is the second-largest maker of smartphones in the world, behind South Korea’s Samsung. By designing chipsets and the handsets they talk to, experts argue, Huawei may have an edge in getting 5G products to market more quickly.
When 3G and 4G networks were being built, Huawei was playing catch-up to its established rivals, licensing much of their technology. To some extent, that lured Ericsson and Nokia, which today are Huawei’s main rivals in the race to develop 5G,into a state of complacency, said Thillien of Fitch Solutions. They had invested a lot of money into what were then cutting-edge technologies and sought to squeeze the most they could out of them rather than racing ahead to the next stage, making their own developments obsolete. At the same time, they felt they had little to fear from what was then regarded as a nonthreatening Chinese firm.
Now, the situation is reversed. Huawei has more 5G-related patents than any other firm, according to IPlytics, a German-based company that tracks intellectual property development. That means other companies will have to pay Huawei to use key bits of 5G technology.
Huawei has been able to shape the rules of the road for 5G in a way it never could with earlier mobile technologies.
Partly as a result of that technological arsenal, Huawei has been able to shape the rules of the road for 5G in a way it never could with earlier mobile technologies.
Over the past few years, telecoms engineers have regularly gathered every few months to hash out the evolving technical standards that will govern all aspects of 5G. And Huawei has simply flooded the zone, sending more engineers to those meetings than any other telecoms company and making more technical contributions to the still-evolving standard than anyone else, IPlytics found.
Along the way, Huawei has notched an ever-growing tally of technical breakthroughs that no other single company has matched. It has field-tested its 5G technology in lower frequencies (good for coverage) and higher frequencies (better for high data speeds). Earlier this year, it debuted its own, in-house-designed chipset and devices that will make 5G a reality. Huawei says it currently has 30 contracts to build 5G networks around the world, with dozens of other countries close to signing on.
With a Chinese company building the network through which huge volumes of data—phone calls, emails, and business transactions—will flow across the globe, U.S. officials fear that infrastructure could be subverted for espionage, allowing Beijing’s intelligence agencies to gather huge volumes of communications.
Even more dire, Washington fears that Beijing will replace it as the world’s premier intelligence power and perhaps even deny it access to the networks that make global commerce and the projection of military power possible. For decades, U.S. intelligence agencies have capitalized on the central role of U.S. companies in global telecommunications networks to spy on adversaries and gather crucial intelligence.
And now, whether by design or luck or some combination of the two, the Chinese Communist Party may have the means to overturn that disadvantage—especially because the United States itself, despite the prominence of Silicon Valley, doesn’t have a national champion of its own developing 5G. Consolidation and mergers in the telecommunications industry have made European, not American, companies the leading Western makers of the boxes, antennas, and beam-generating equipment that will serve as the backbone of 5G technology.
“If you’re the government of China, you have a couple of choices: You can duplicate what the U.S. did and build a multibillion-dollar signals intelligence network, or you can fund Huawei—and that’s a lot cheaper,” said James Lewis, the director of the Technology Policy Program at the Center for Strategic and International Studies.
Foreign production of advanced communication networks “will challenge U.S. competitiveness and data security,” and as American data increasingly flows across those networks, that will increase “the risk of foreign access and denial of service,” Dan Coats, the director of national intelligence, warned in his annual assessment of threats facing the United States.
As a result of these fears, Washington has essentially banned Huawei equipment inside the United States. Last December, the Justice Department also ordered the arrest of Meng Wanzhou, Huawei’s chief financial officer and Ren’s daughter, on charges of trying to steal American technology and lying about the company’s business in Iran. She is currently fighting extradition to the United States from Canada.
But Washington may be fighting a losing battle in frantically trying to get its Western allies to swear off Huawei as well. So dominant has Huawei already become in building telecom networks globally and vying to set the world standard for 5G that the Trump administration finds itself somewhat isolated, even among its closest allies.
Despite U.S. pressure, the European Union has opted against barring the Chinese firm, and even close U.S. allies such as Britain and Germany, which are still deciding which companies will participate in building their 5G networks, are unlikely to ban Huawei altogether. The reason is simple: For many European countries that already use Huawei equipment in their 4G networks, it would be costly to switch horses in midstream.
U.S. policymakers have leaned especially hard on Germany, even warning Berlin it could lose access to U.S. intelligence sharing if it includes Huawei in its network.
“Europe is very much a battleground, and Germany is a battleground within the battleground.”
“Europe is very much a battleground, and Germany is a battleground within the battleground,” said Thillien of Fitch Solutions.
Yet the Trump administration has done a poor job, by most accounts, of convincing European allies of the security risk posed by the company—a problem exacerbated by the president’s constant sniping at his counterparts across the Atlantic. Washington has never publicly presented evidence backing up its assertions that Huawei equipment plays a role in Chinese espionage operations, and there are doubts that it has shared much evidence in private either.
According to Schrader of the German Marshall Fund, if U.S. intelligence officials truly had clear evidence that Huawei was helping China to spy, they would be more “forward leaning” in sharing that information with allies.
With the American campaign faltering, U.S. intelligence officials are already beginning to prepare for a world in which Huawei dominates next-generation telecommunications networks. “We are going to have to figure out a way in a 5G world that we’re able to manage the risks in a diverse network that includes technology that we can’t trust,” said Sue Gordon, the principal deputy director of national intelligence, in remarks last month. “You have to presume a dirty network.”
Huawei executives argue the U.S. allegations are irresponsible, and the company’s founder has said he would defy Chinese law on intelligence gathering to maintain his company’s independence. It is a claim China experts find laughable.
“The bigger a company in China gets, the more it needs to align its business goals with the party’s political goals,” said Schrader. “The mere fact that Huawei is able to publicly take a position so at odds with the actual reality of China speaks to the degree of party support it enjoys. ‘Normal’ businesses in China cannot get away with saying they don’t abide by party dictates.”
To satisfy the demands of law enforcement, telecommunications networks are typically built to enable some type of wiretapping function. Such abilities have in the past been subverted by intelligence agencies to snoop on calls and scoop up data, so using Chinese-designed equipment for such networks practically represents an invitation to Beijing to spy, “since the infrastructure itself is designed to support such meddling,” argued Nicholas Weaver, a senior researcher at the International Computer Science Institute.
In an interview with Foreign Policy, Andy Purdy, Huawei’s chief security officer in the United States, pointed out that U.S. espionage activities documented by National Security Agency whistleblower Edward Snowden have created a fundamental attitude of distrust in the telecommunications industry. The Snowden disclosures exposed how American companies were forced to cooperate with U.S. intelligence activities.
“The U.S. fundamentally believes that China would use Chinese companies—even private ones—for the same kinds of things that the U.S. uses American companies for,” Purdy said.
Huawei executives have even begun to taunt Washington over Trump’s warnings that the United States is falling behind in 5G technology. “The U.S. is lagging behind,” Huawei rotating chairman Guo Ping told reporters earlier this year. “His message is clear and correct.”
At the same time, many experts say security fears singling out Huawei equipment are overblown, as nearly all the big telecom equipment makers use Chinese factories to churn out their components.
“The whole Huawei security discussion as it is now is kind of silly and misses the point,” said Ruhlig of the Swedish Institute of International Affairs. “It’s fair to assume that China could hack into 5G anyway, whether you have Huawei equipment in place” or that of another manufacturer, he said. “Banning Huawei will not by itself provide additional security.”
That line of thinking has Huawei officials asking Washington to have another look at its technology. “Let’s talk about proven risk mitigation mechanisms so that we can have a chance to do business in the United States,” Purdy said. The U.S. government, however, has yet to respond to that overture.
Experts are also still debating whether Huawei is as dominant as some officials in Washington fear. Some telecoms executives with experience operating Huawei alongside equipment made by other manufacturers say that it has established the lead, especially in the bread-and-butter technology of transmitting large amounts of data through radio networks.
“From a technology point of view, our view is that specifically in [radio access networks] we see Huawei with a big advantage, a couple of years ahead of any other provider,” said one Western executive who operates a major national mobile network.
Others say Huawei’s purported technical lead may be much smaller, and in any event is hard to measure when so many companies are making progress in different pieces of the 5G puzzle. 5G networks are made up of many different technologies, many of which remain in a nascent stage of development. Engineering task forces are still determining the standards—the technical language different devices will use to talk to one another and exchange data. That means determining who is ahead in the market is more art than science.
“What is meant by being ahead?” said Thelander of the Signals Research Group. “I’m not sure how you define being ahead.”
The previous shift in mobile communications technology—from 3G to 4G and beyond—powered the creation of the current app-based technology. Streaming services such as YouTube and Spotify, which deliver high-fidelity content into users’ smartphones, rely on the technology, as do networked car-hailing services such as Uber. But that transition was more an evolution than a revolution; 5G, while building on existing cellular technologies, represents a breakthrough in the amount of data that can be transmitted, and especially its speed and reliability.
These improvements in speed and reliability are required for the kinds of innovations that technology executives tout as the next phase of the internet revolution. For self-driving cars to become a reality, they will require reliable high-bandwidth connections and near-instantaneous data transmission to be able to react to changing road conditions in milliseconds. Advances in artificial intelligence and machine learning likewise require huge datasets to function as intended.
And whether Huawei is a year ahead of its peers, or a few months ahead, or roughly at the same level may not be the biggest question. 5G is still being developed, and commercial rollout in a limited fashion won’t begin in earnest until next year; the first true 5G networks, which will deliver all the whiz-bang features the technology promises, probably won’t arrive until 2025 at the earliest.
Huawei’s leading role in shaping the most important new technology standard will likely pay dividends in terms of billions of dollars in license fees and could give the Chinese firm an advantage as countries around the world scramble to build 5G networks.
“In the developing world, China is internationalizing Chinese technology standards,”
“Whoever sets the standard is going to grab higher market share,” said Ruhlig of the Swedish Institute of International Affairs. That’s already on display in parts of Asia, Africa, and the Middle East, where Huawei rules. “In the developing world, China is internationalizing Chinese technology standards.” he said.
Indeed, as countries around the world scramble to start building advanced telecoms networks, and despite the U.S. campaign against the company,Huawei is becoming an even more entrenched player. Asian countries including Malaysia, Vietnam, and U.S. ally Thailand are all considering Huawei for their 5G networks. So are European and NATO allies of the United States such as Spain, Portugal, Italy, and Hungary, while Germany and the United Kingdom are unlikely to ban it altogether.
For almost 200 years, China has largely been on the receiving end of technology developed elsewhere. Today, it is reasserting, in the most demonstrable way, the technological leadership it enjoyed long ago.


 The ceaseless battle over the 2010 law has made it difficult to address the high cost of American health care.
 Foreign Policy illustration

